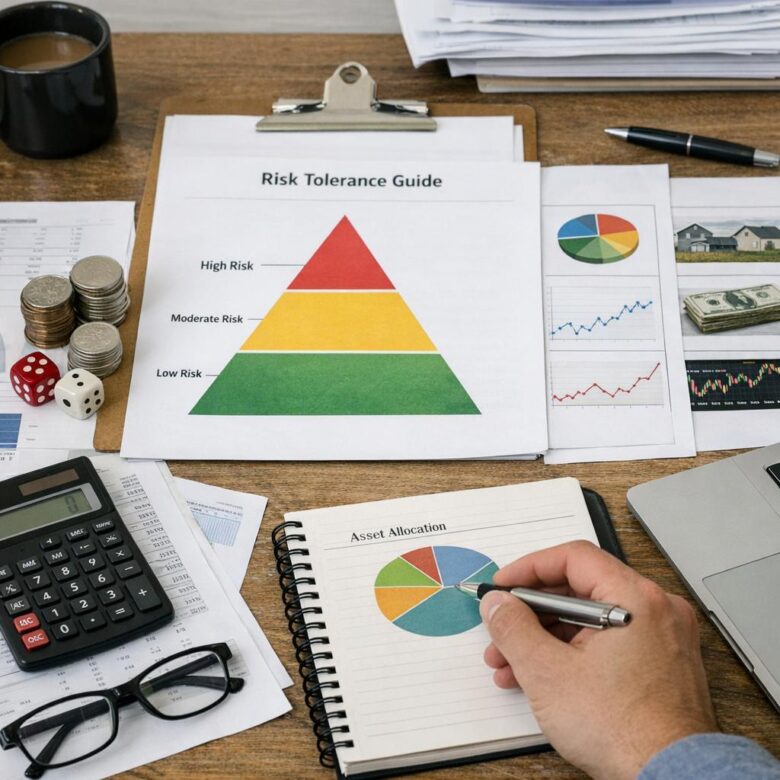
Risk tolerance helps you decide how much investment uncertainty you can accept. But willingness to take risk is only part of the decision: your goals, withdrawal dates and ability to absorb losses matter too. [1]
This guide uses U.S. account and deposit-insurance examples.
Risk tolerance and risk capacity are different
Risk tolerance is often defined broadly as your willingness and ability to accept investment losses. For planning purposes, it helps to separate those two parts:
- Willingness: How comfortable are you with uncertainty, falling account values and the possibility of losing money?
- Capacity: How much loss can your finances absorb without jeopardizing essential spending or an important goal?
Someone can feel comfortable taking substantial risk but have little capacity for it because they need the money soon. Conversely, someone with strong finances and decades to invest may still find large market swings difficult to tolerate. Both considerations belong in the decision. [1]
Assess risk one goal at a time
Rather than giving all your money one label, answer these questions for each goal:
- How much money will you need, and when?
- Could you delay the goal or reduce its cost after a loss?
- Would a job loss or unexpected expense force you to withdraw early?
- How did you respond to previous investment losses, if you have experienced them?
These questions connect your investment choices to your spending needs and financial circumstances. [1] If unexpected expenses could disrupt your plan, review emergency savings versus investing before deciding how much to commit to long-term investments.
Translate a potential decline into dollars
As an illustrative stress test, suppose a $50,000 portfolio falls 20%. Its value becomes $40,000—a $10,000 decline. Recovering from $40,000 to $50,000 requires a 25% gain, ignoring contributions, withdrawals, fees and taxes.
Would you need to sell to cover bills? Would the loss change your goal? Could you remain invested if the decline deepened? This is a thought exercise, not a forecast or a worst-case limit. A long holding period does not guarantee recovery by the date you need the money. [2]
A risk questionnaire can provide a starting point, but its suggested allocation is not a complete plan. Investor.gov also cautions that results may favor products or services sold by the questionnaire’s provider. [3]
Match your asset allocation to the goal
Asset allocation means dividing your investments among assets such as stocks, bonds and cash. Your timeline and risk tolerance should shape that mix—not your age alone or a label such as “moderate.” [3]
The following examples illustrate the trade-offs, rather than prescribe a portfolio:
| Illustrative goal | Main consideration |
|---|---|
| Home down payment in two years | Preserving the required amount and keeping it accessible generally matter more than pursuing growth. |
| Flexible purchase in seven years | A stock-and-bond mix may be worth considering, but the acceptable risk depends on whether the purchase can wait. |
| Retirement spending decades away | Stocks may play a larger role if your finances and comfort with losses support it. Time does not eliminate risk. |
The same person can reasonably use different allocations for these goals. A fixed withdrawal deadline leaves less room to wait through a downturn than a flexible one. [3] Even long-term stock investments can suffer substantial losses. [2]
Look beyond “conservative” and “aggressive” labels
The investments inside an allocation matter as much as the label:
- Bank deposits and money market funds are different. Eligible savings and money market deposit accounts at FDIC-insured banks have deposit protection within applicable limits. Money market mutual funds do not have FDIC insurance, even when used to hold cash in a brokerage account. [6]
- Bond funds can lose money. Rising interest rates generally reduce bond values, and issuers can fail to repay their debts. Funds holding longer-maturity bonds are generally more sensitive to interest-rate changes than those holding shorter-maturity bonds. Even a government-bond fund is not a guaranteed cash balance. [5]
- A higher stock allocation does not require concentrated bets. A portfolio dominated by one company or industry carries concentration risk. Being comfortable with volatility does not remove that risk. [2]
Broad funds can help spread investments across companies and sectors, but a narrowly focused ETF or mutual fund may not provide much diversification. Check what each fund owns, not just how many funds you hold. [3] See how portfolio diversification works for a closer look.
Taking very little market risk also involves a trade-off: cash returns may not keep pace with inflation or provide enough growth for a long-term goal. [4] If your plan appears to require more risk than you can afford, revisit the savings amount, target cost or deadline rather than simply choosing riskier investments.
Review the plan without reacting to every headline
Write down your target allocation and a review schedule. An annual check is one practical approach; also revisit the plan when your income, spending needs or goal changes. A review does not necessarily require a trade. [4]
Rebalancing brings a portfolio back toward its target mix after investment performance changes the proportions. You may be able to direct new contributions toward underweight assets instead of selling. Before trading, consider transaction costs and potential tax consequences. [4]
Avoid increasing risk merely because an investment has recently performed well. Change the allocation when the plan’s assumptions change—not simply because a different investment looks more exciting. [4]
Before choosing investments, aim to explain four things clearly: what the money is for, when you need it, what a loss would mean and why the proposed mix fits those constraints.
Sources & References
- FINRA: Know Your Risk Tolerance
- FINRA: Investment Risk, Time Horizons and Concentration
- SEC Investor.gov: Asset Allocation and Diversification
- SEC Investor.gov: Beginners’ Guide to Asset Allocation, Diversification and Rebalancing
- SEC Investor.gov: Bond Funds and Income Funds—Investment Risks
- SEC Investor.gov: Cash Sweep Programs—Bank Deposits, Money Market Funds and Insurance
Invstoc publishes educational content about personal finance and investing. Articles are researched using primary and authoritative sources when relevant, with a focus on explaining concepts, trade-offs and risks clearly. The content is general education, not individualized investment, tax or legal advice.